The 3.6% Premium: Resilience and ROI Through Shared Intelligence and AI
Most of a company’s sustainability impact sits in its supply chain. So does the business case.
What the discussion at ReThink HK 2026 revealed about resilience, supplier intelligence and proving commercial value.
Sustainability teams are being asked to deliver more with less. Climate targets are public, the pressure on operating costs has not eased, and boards increasingly expect evidence that sustainability programmes are reducing risk and creating value. Yet much of the impact businesses need to manage sits outside their own operations, across supply networks they do not directly control.
That was the starting point for the EcoVadis roundtable at ReThink HK 2026, held on 11 September in Hong Kong. We brought together sustainability, procurement and risk professionals to consider what it takes to turn supply chain sustainability from a reporting obligation into better business decisions. The conversation drew on findings from the Sustainable Procurement Barometer 2026 and the practical experience of leaders in the room.
Four shifts are raising the stakes
The footprint remains upstream. Carbon continues to be a leading priority for sustainable procurement. In the Barometer, 54% of organisations put it among their top three priorities. But the supplier data needed to act on that ambition is still incomplete. Nearly 90% of organisations have visibility into less than half their Tier 2 suppliers, leaving significant blind spots across carbon and human rights risk.
Supply networks are changing. Trade tensions, geopolitical disruption and extreme weather are pushing companies to diversify sourcing and production. That may reduce dependence on individual suppliers, but it also brings new partners, markets and risks into scope. Sustainability teams need to assess a broader supply base while keeping pace with commercial decisions.
Regulatory expectations are diverging. Rules, reporting requirements and implementation timelines differ across markets. That makes it harder to plan against a single, stable rulebook. It does not reduce the need for dependable supplier information. Businesses still need to know where their exposure lies and what actions to take, regardless of how individual requirements evolve.
AI is expanding what teams can do. New tools can accelerate analysis, identify patterns and help prioritise action across complex supplier networks. But they cannot compensate for missing or unreliable data. The quality of the decisions still depends on the quality of the supplier intelligence behind them.
Taken together, these shifts lead to two questions: can companies build the supplier visibility needed to manage the risks, and can they demonstrate to finance that acting on those risks delivers measurable business value?
A more commercial conversation in Hong Kong
The discussion in Hong Kong suggested that this shift is already under way. In our live poll, risk assessment and brand reputation or business opportunities were tied as the main drivers of sustainable procurement, each selected by 33% of respondents. Regulation was the primary driver for 11%. This was a small group, but the direction was clear: participants were thinking about commercial outcomes as well as compliance.
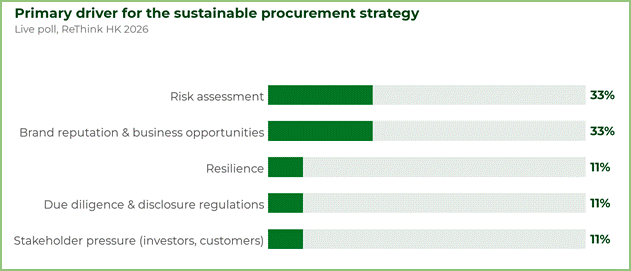
Source: EcoVadis roundtable live poll, ReThink HK 2026
The same group was not starting from scratch. In a second poll, 41% of respondents said sustainability was already embedded in procurement processes, while 24% were working to quantify its effectiveness and impact. Those are different stages of maturity, but both bring the conversation closer to performance and return.
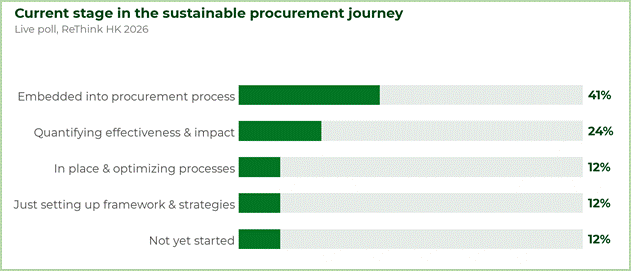
Source: EcoVadis roundtable live poll, ReThink HK 2026
The global Barometer provides a wider perspective. Among the multinational companies surveyed, regulatory preparedness was cited as a benefit of sustainable procurement by 69%, followed by risk reduction at 62% and innovation at 57%. The questions asked were different, but together the findings underline how broad the business case has become.
Why the 3.6% resilience premium matters
One finding from the Barometer deserves particular attention: more resilient organisations reported 3.6% higher revenue growth than their less resilient peers. It is an observed difference, not a promise that a sustainability investment will produce a fixed return. But it puts the financial relevance of resilience into sharper focus.
The research also found a difference in how more mature organisations measure value. Comparing the top 10% of respondents under the Barometer’s maturity methodology with the rest:
- 81% versus 67% quantify financial ROI from sustainable procurement initiatives.
- 47% versus 27% track sustainability-enhanced revenue growth and profitability.
- 85% versus 65% have begun collecting product-level carbon data from suppliers.
The lesson is not that collecting more metrics automatically creates value. It is that mature programmes are more likely to connect sustainability performance with business outcomes. That matters when investment decisions are being made alongside competing operational priorities.
Visibility only matters when it changes decisions
Reliable information is still one of the biggest obstacles. In the Barometer, 69% of organisations named a lack of supplier data as a barrier to sustainable procurement investment. The challenge becomes more pronounced as companies move beyond Tier 1 suppliers or begin to measure product-level impacts.
Even when data is available, it does not always reach the decisions that matter. Regional figures shared during the session showed that 58% of companies in mainland China had visibility into at least 75% of their Tier 1 suppliers. Yet only 24% integrated ESG metrics into procurement decisions. Visibility is necessary, but it is not the same as action.
There is also a gap between what buyers request and what suppliers are able or motivated to deliver. The supplier findings in the Barometer show that 30% provide no primary emissions data to customers. Only 17% feel incentivised by customer sustainability initiatives. And 51% want buyers to make the link between sustainability and commercial outcomes more explicit.
That is an important distinction. Asking suppliers for more information may improve reporting coverage. It will not, on its own, build the capabilities or incentives needed for improvement. The commercial relationship has to be part of the solution.
Shared intelligence can close the gap
The most effective programmes are moving from isolated assessments to information that buyers and suppliers can use together. Independent, comparable supplier intelligence allows procurement and sustainability teams to work from a common view of performance, while helping suppliers demonstrate progress to multiple customers without starting again each time.
This is the role EcoVadis plays: enabling organisations to understand supplier sustainability performance, prioritise the areas that matter and track progress over time. The aim is not simply to collect another data point. It is to put trustworthy information into sourcing, supplier engagement and risk decisions.
The Barometer found that organisations with high sustainability intelligence were 3.6 times more likely to engage suppliers strategically. That is a useful reminder that the value of information increases when it supports a more productive relationship between buyer and supplier.
What this looks like in practice
Schneider Electric, featured in the Barometer, offers a practical example. Its top 1,000 suppliers account for approximately 65% of supply chain emissions. Rather than treating decarbonisation as a reporting exercise alone, it focuses supplier engagement on energy efficiency, waste reduction and operational improvements that can generate savings. Progress is reviewed quarterly and linked to incentives.
The principle is straightforward: suppliers need to see a business reason to make the changes their customers are asking for. As Christophe Quiquempoix, VP Sustainable Procurement at Schneider Electric, puts it in the Barometer: “Sustainability is about doing the same, or more, with less. That’s the ROI story suppliers can act on.”
In Hong Kong, our customer panel with CLP, Swire Properties and Asahi Global Procurement brought the discussion into the regional context, sharing their experiences of building supplier sustainability programmes across Asia-Pacific. Three messages stood out: don’t wait for perfect data to get started, consider the supplier’s perspective, and build internal support to sustain progress.
Read the three takeaways from our customer panel at ReThink HK.
The next conversation is about value
The pressure on supply chains is unlikely to ease. Companies will continue to diversify sourcing, respond to shifting regulatory expectations and invest in better ways to understand supplier performance. Finance teams will continue to ask which initiatives protect the business, improve efficiency and deserve investment.
For sustainability leaders, the opportunity is to make that connection visible. Show where supplier intelligence changes a sourcing decision. Identify where engagement reduces exposure or operating costs. Demonstrate progress in terms the business already uses.
The 3.6% figure is not a shortcut to the business case. It is a reason to ask better questions about resilience, and to measure the decisions that follow. The strongest programmes will be those that can move convincingly from data to action, and from action to value.
That is also the thinking behind the EcoVadis CSO Challenger, an interactive leadership session designed to explore the choices and trade-offs involved in making the commercial case for sustainability. For teams looking to bring sustainability, procurement and finance into a more practical conversation, it is a way to explore the issues together.
Thank you to everyone who joined us in Hong Kong, to our customer speakers from CLP, Swire Properties and Asahi Global Procurement, and to the ReThink HK team for hosting.